A Beginner's Guide to Building an Emergency Fund
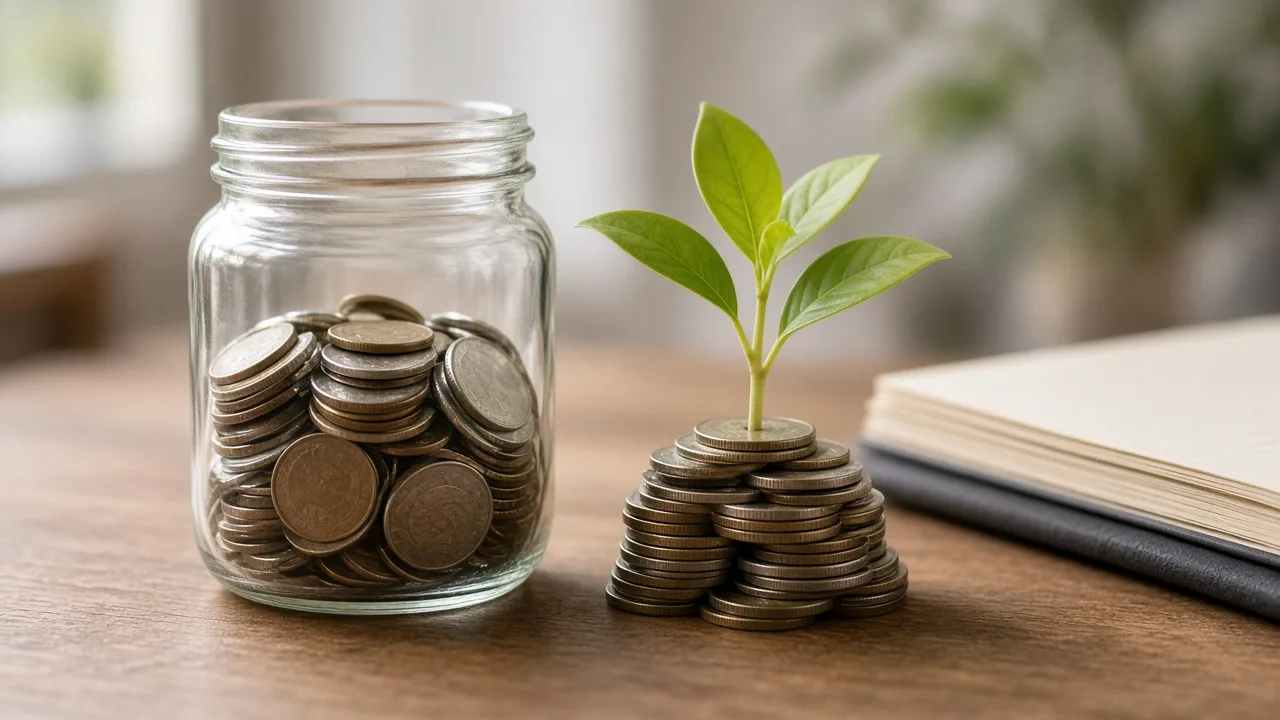
Car repairs, medical bills and sudden job changes rarely arrive at a convenient time. An emergency fund is a cushion of cash set aside for exactly those moments. It can keep a surprise expense from becoming credit card debt and give you breathing room when life changes unexpectedly.
How Much Should You Save?
A common guideline is to build up three to six months of essential living expenses, such as housing, utilities, food, transportation, insurance and minimum debt payments. If your income is irregular or you support others, you may want a larger cushion. If that goal feels distant, start with a smaller milestone such as one month of expenses, or even a few hundred dollars. Every dollar helps.
Where to Keep the Money
An emergency fund should be safe and easy to reach. A separate high-yield savings account at a federally insured bank or credit union is a popular choice because it earns interest while keeping funds available. Avoid putting it into investments that can lose value or have penalties for early withdrawal.
Start Small and Automate
- Open a dedicated savings account so the money is separate from your daily spending.
- Set up an automatic transfer on payday, even if it is a modest amount.
- Direct windfalls such as tax refunds, bonuses or gifts into the fund.
- Review small recurring expenses and redirect savings from subscriptions you no longer use.
What Counts as an Emergency?
Decide in advance what the fund is for. True emergencies include essential car or home repairs, urgent medical costs and loss of income. Vacations, sales and planned purchases belong in separate savings categories. Having clear rules makes it easier to resist dipping into the money.
Rebuild After You Use It
If you do need to use the fund, that is exactly what it is for. Once the emergency has passed, resume automatic transfers until the balance is back to your target.
Balance With Other Goals
Many people build a starter fund while also paying down high-interest debt and contributing enough to a workplace retirement plan to earn any employer match. The right order depends on your situation, so consider talking with a financial professional or a nonprofit credit counselor.
Stay Motivated
Track your progress with a simple chart or a savings tracker, and celebrate milestones such as your first $500 or your first full month of expenses. Seeing the balance grow makes it easier to stay consistent, even when other expenses compete for your attention.
This article is for general information only and is not personalized financial advice.
Comments are closed.